I didn’t expect my new roof to cost ₹2.5 lakh, and the expense made me take a closer look at my home improvement budget. During a conversation with my accountant, I learned that certain home improvements may qualify for tax deductions or tax credits, depending on the type of project and applicable tax rules.
Until then, I had never considered the potential tax benefits of home improvements.
I had spent years improving my home—new windows, a kitchen remodel, a home office setup—and I had never once thought about the tax implications. I was leaving money on the table.
I started researching home improvement tax deductions. But honestly? It was confusing. Some articles said improvements were deductible. Others said they weren’t. I didn’t know who to believe.
I made mistakes. I assumed my new kitchen was fully deductible (it wasn’t). I forgot to keep receipts for energy-efficient upgrades. I missed out on deductions I was actually eligible for.
But after months of research and working with a tax professional, I finally figured out how home improvement tax deductions actually work.
Today, I want to share my 7 best tips with you. These are practical, legitimate, and designed to help you save money on your taxes. Let’s dive in.
My First Lesson – The Difference Between Improvements and Repairs
Before we get into the specific deductions, let me share the most important thing I learned.
Most home improvements are NOT tax deductible in the year you make them.
This was a shock to me. I thought every rupee I spent on my home would reduce my tax bill. But that’s not how it works.
Here’s the key distinction:
Home Repairs:
- Maintain your home’s current condition
- Examples: painting, fixing a leaky faucet, patching a hole in the wall
- Generally not deductible for your primary home
Home Improvements (Capital Improvements):
- Add value to your home, prolong its life, or adapt it to new uses
- Examples: new roof, kitchen remodel, adding a room, installing solar panels
- Not immediately deductible, but they increase your home’s “basis”
What does “basis” mean?
Your basis is essentially the value of your home for tax purposes. When you sell your home, your basis is subtracted from the sale price to determine your capital gain (profit). A higher basis means a lower taxable gain .
For example, if you bought your home for ₹50 lakh and made ₹10 lakh in improvements, your basis is now ₹60 lakh. If you sell for ₹80 lakh, your taxable gain is ₹20 lakh, not ₹30 lakh .
This is the single most important concept in home improvement tax deductions.
Read Also: Decorating a Double Height Living Room: 7 Stunning Ideas for Tall Spaces
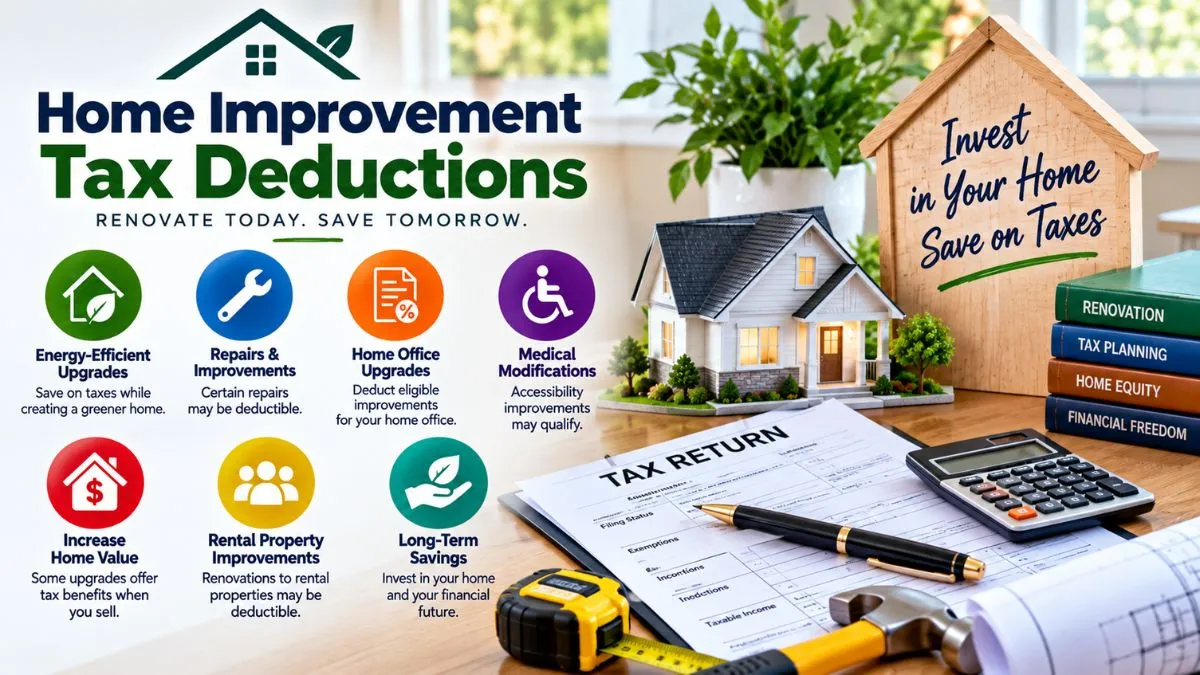
7 Home Improvement Tax Deductions and Credits You Need to Know
1. Energy-Efficient Home Improvements
This is one of the few areas where you can get an immediate tax benefit for home improvements.
What qualifies:
- Solar panels, solar water heaters, and battery storage (30% credit, no cap)
- Geothermal heat pumps, small wind turbines (30% credit)
- Insulation, energy-efficient windows and doors, heat pumps (up to ₹3,200/year)
My Story:
I installed energy-efficient windows throughout my home. It cost me ₹1.5 lakh. I claimed the energy tax credit and saved over ₹30,000 on my taxes. It was a significant chunk of the cost.
Important Note:
Many older articles mention federal energy credits that have been repealed for new projects. Under recent tax law changes, projects placed in service after the cutoff no longer qualify for the federal credit . Check with your tax professional about current rules.
What you can do:
- Check state and local energy programs—many still offer rebates
- Check with your utility company for rebates on efficient equipment
- Keep all receipts and manufacturer certification statements
Cost Check: Varies by project, but the tax credit can be substantial.
2. Medically Necessary Home Improvements
If you need to modify your home for medical reasons, those expenses may be deductible as medical expenses.
What qualifies:
- Wheelchair ramps
- Widened doorways and hallways
- Handrails and grab bars
- Accessible bathrooms (roll-in showers, lowered cabinets)
- Medical lifts or elevators
My Story:
My father needed a wheelchair ramp installed at our home. It cost ₹45,000. Our tax professional helped us deduct it as a medical expense. It was a huge relief during a difficult time.
Important Note:
The modification must be medically necessary and prescribed by a doctor. Purely aesthetic upgrades don’t qualify. Also, any portion of the cost that increases your home’s value may reduce the deductible amount .
What you can do:
- Get a written prescription from your doctor
- Keep all invoices and receipts
- Work with a tax professional to calculate the deductible portion
Cost Check: ₹20,000 to ₹2,00,000+ depending on the modification.
3. Home Office Renovations (If You’re Self-Employed)
If you’re self-employed and work from home, renovations to your home office may be deductible.
What qualifies:
- Improvements to a dedicated home office space
- A separate structure on the property (like an office shed or accessory dwelling unit)
- A portion of mortgage interest, insurance, utilities, repairs, and depreciation for the business portion
My Story:
I’m self-employed, and I converted a spare room into a dedicated home office. I added better lighting, built-in shelves, and a new desk. My tax professional helped me deduct a portion of these expenses. It saved me thousands.
Important Note:
You must be self-employed or a small business owner. If you’re a salaried employee, you cannot claim this deduction, even if you work from home . The space must be used regularly and exclusively for business .
What you can do:
- Measure your office space and calculate the percentage of your home it occupies
- Track all expenses related to the office
- Use the simplified method or actual expense method
Cost Check: Varies, but can be substantial if you have a dedicated office.
4. Rental Property Improvements
If you own a rental property, the rules are different—and more favorable.
What qualifies:
- Repairs to a rental property are deductible in the year you make them
- Improvements to a rental property are capitalized and recovered through depreciation over time (usually 27.5 years)
My Story:
I own a small rental apartment. When a tenant moved out, I had to fix a leaky faucet and repaint the walls. These were repairs, and I deducted them in full that year. When I later replaced the entire flooring, that was an improvement, and I depreciated it over time.
What you can do:
- Keep detailed records of all repairs and improvements
- Understand the difference between repairs (deductible now) and improvements (depreciated)
- Use IRS Tax Form 4562 for depreciation
Cost Check: Varies by property and project.
5. Interest on Home Improvement Loans
If you take out a loan to fund home improvements, the interest you pay may be deductible.
In India:
- Under Section 24(b) of the Income Tax Act, interest on a home renovation loan is deductible
- For a self-occupied property, the deduction limit is ₹30,000 per year
- For a let-out property, there is no upper limit on the interest deduction
- The principal repayment does not qualify for deduction under Section 80C
My Story:
I took out a top-up loan on my home loan to fund a kitchen renovation. The interest I paid was deductible under Section 24(b). It wasn’t a huge amount (₹30,000 limit for self-occupied), but it was better than nothing.
Important Note:
The tax treatment depends on the purpose of the loan. If you use the money for personal expenses (like paying off credit cards), the interest is not deductible . The loan must be used for substantial improvements to the home that secures it .
What you can do:
- Keep documentation showing the loan was used for home improvements
- Get an interest certificate from your lender
- Consult a tax professional about your specific situation
Cost Check: The deduction can save you up to ₹30,000 in taxable income (for self-occupied) or more for rental properties.
6. Reducing Capital Gains Tax Through Improvements
This is the “quiet workhorse” of home improvement tax deductions. Even if you can’t deduct improvements now, they can reduce your tax bill when you sell.
How it works:
- Home improvements increase your home’s basis
- A higher basis means a lower capital gain when you sell
- In India, under Section 48 of the Income Tax Act, the cost of improvement is deductible from capital gains
- You can also use the Cost Inflation Index (CII) to adjust your improvement costs for inflation
My Story:
I bought my first home for ₹40 lakh. Over five years, I spent ₹8 lakh on improvements—a new kitchen, flooring, and built-in wardrobes. When I sold for ₹70 lakh, my taxable gain was calculated on ₹62 lakh (₹70L – ₹40L – ₹8L), not ₹70 lakh. The improvements saved me a significant amount in capital gains tax.
Important Note:
- Routine repairs and maintenance (like painting) do not count as improvements for capital gains purposes
- Structural changes, permanent fittings, and value-adding renovations do count
- Keep GST-compliant invoices and bank entries for all improvements
What you can do:
- Maintain a “Property Improvement File” with all receipts and invoices
- Keep records for as long as you own the property (and several years after selling)
- Consult a tax professional when calculating capital gains
Cost Check: The savings depend on your property’s appreciation and the amount of improvements.
7. The Home Sale Exemption (US Context)
If you’re in the US, there’s an additional benefit to consider.
How it works:
- If you sell your primary residence for a profit, you may be able to exclude up to $250,000** (single) or **$500,000 (married filing jointly) from capital gains tax
- Home improvements increase your basis, which can help you stay under this exclusion threshold
My Story:
A friend of mine in the US sold her home for a $300,000 profit. She had made $50,000 in improvements over the years. By increasing her basis, she was able to reduce her taxable gain and qualify for a larger exclusion. She saved tens of thousands in taxes.
What you can do:
- Keep detailed records of all improvements
- Work with a tax professional to calculate your adjusted basis
- Understand the exclusion limits for your filing status
Cost Check: Potentially saves thousands in capital gains tax.
Common Mistakes to Avoid (I Made All of These)
- Confusing repairs with improvements: I thought painting my house was a “home improvement.” It’s a repair, and it’s not deductible. Know the difference .
- Not keeping receipts: I lost receipts for several energy-efficient upgrades. Without documentation, I couldn’t claim the credits.
- Assuming everything is deductible: Most home improvements are not immediately deductible. They increase your basis, which helps when you sell .
- Forgetting about itemization: In the US, deductions only help if you itemize. If you take the standard deduction, you won’t benefit . In India, the old tax regime allows these deductions; the new regime does not .
- Not consulting a tax professional: I tried to figure it out myself and made mistakes. A good tax professional can save you far more than their fee.
Frequently Asked Questions (FAQs)
1. Are home improvements tax deductible?
Most home improvements are not immediately deductible for your primary home. However, they increase your home’s basis, which reduces capital gains tax when you sell. Some exceptions exist, including energy-efficient upgrades, medically necessary modifications, and home office renovations for self-employed individuals .
2. What is the difference between a repair and an improvement?
A repair maintains your home’s current condition (e.g., fixing a leak, painting). An improvement adds value, prolongs life, or adapts the home to new uses (e.g., new roof, kitchen remodel) .
3. Can I deduct interest on a home improvement loan in India?
Yes, under Section 24(b) of the Income Tax Act, interest on a home renovation loan is deductible. For a self-occupied property, the limit is ₹30,000 per year. For a let-out property, there is no upper limit .
4. Can I deduct my new kitchen?
Generally, no—not immediately. A kitchen remodel is a capital improvement that increases your home’s basis. It will reduce your capital gains tax when you sell, but it’s not a current-year deduction .
5. What home improvements qualify for tax credits?
Energy-efficient improvements (solar panels, geothermal heat pumps, insulation, windows) may qualify for tax credits. Medically necessary modifications may be deductible as medical expenses. Home office renovations may be deductible if you’re self-employed .
6. Do I need to itemize to claim these deductions?
In the US, yes—you must itemize deductions on Schedule A to claim home improvement loan interest and medical expense deductions . In India, you must opt for the old tax regime to claim these deductions .
Over to You – Start Planning Now
If you’re planning home improvements, don’t wait until tax time to think about the tax implications. Start planning now.
Keep every receipt. Document every project. Understand the difference between repairs and improvements. And most importantly, consult a qualified tax professional who understands your specific situation.
I remember the first year I worked with a tax professional on my home improvement deductions. I saved far more than I expected—and I learned how to plan better for future projects.
Ultimately, home improvement tax deductions are about being smart with your money. You’re already investing in your home. Why not get every legitimate tax benefit you’re entitled to?
So go ahead. Start that “Property Improvement File” today. Your future self will thank you.
Happy Renovating,
Sankar
(Founder, MyDecorideas.in)